
We aint done yet.. Expect another one.
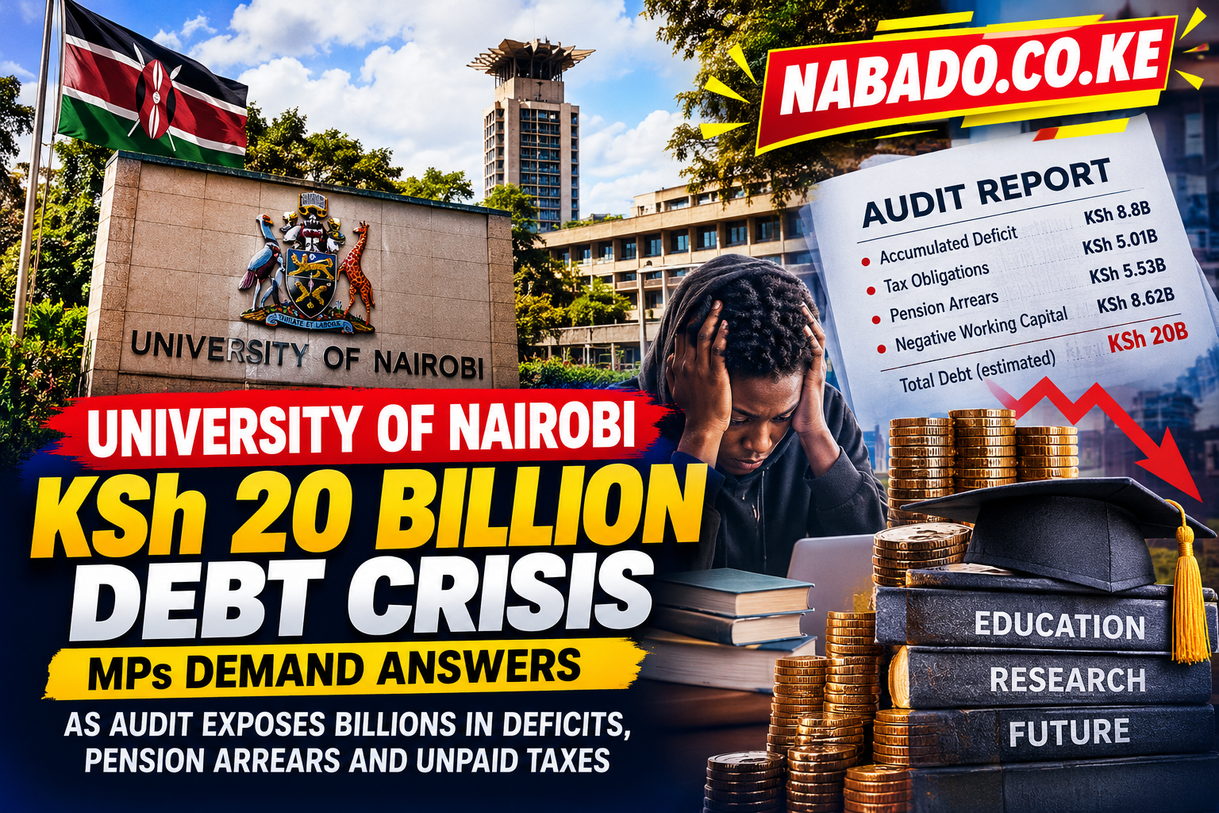
The University of Nairobi is facing renewed scrutiny over its financial position after lawmakers demanded a detailed plan to address an estimated KSh 20 billion debt burden, raising questions about the future of one of Kenya’s oldest and most prestigious institutions of higher learning.
The financial crisis came under the spotlight after the National Assembly Public Investments Committee on Governance and Education questioned university management over audit findings covering several financial years. The committee wants the institution to demonstrate how it intends to restore financial stability, settle outstanding obligations and protect its core academic activities.
The latest developments have placed Vice-Chancellor Professor Ayub Gitau and his management team under pressure to explain how the university accumulated such substantial financial obligations despite holding assets reportedly valued at more than KSh 220 billion.
The controversy has also renewed debate about government funding, expenditure controls, pension arrears and the financial sustainability of public universities in Kenya.
University of Nairobi Debt Crisis: What MPs Want Explained
The National Assembly committee, chaired by Luanda MP Dick Maungu, questioned university officials on October 22, 2026, following concerns raised in reports from the Office of the Auditor-General.
According to reporting by The Star and The Standard, lawmakers want the university to present a practical financial recovery strategy supported by verifiable figures, implementation timelines and measurable targets.
The committee has directed the institution to submit its proposed interventions by December 1, 2026.
The deadline gives the university management an opportunity to explain how it intends to address its outstanding debts while continuing to provide education, conduct research and maintain its facilities.
Lawmakers have raised concerns about accumulated deficits, unpaid statutory deductions, pension contributions and losses recorded by some of the university’s income-generating units.
These problems are particularly significant because the institution serves thousands of students and employs academic, administrative and support staff whose work depends on reliable funding.
The university must also maintain laboratories, libraries, lecture halls, research facilities and other essential infrastructure.
Although management has pointed to its substantial property portfolio as a potential source of financial recovery, MPs want to see evidence that the proposed measures can generate enough revenue to resolve the institution’s immediate and long-term financial obligations.
The debate is therefore no longer limited to the amount of money the university owes. It also concerns the effectiveness of its financial management and the sustainability of its operating model.
Audit Findings Reveal Billions in Accumulated Deficits
The financial difficulties became clearer through the audit findings discussed before lawmakers.
According to reports published by The Star and People Daily, the university recorded a deficit of approximately KSh 2.2 billion during the 2021/2022 financial year. That shortfall pushed its accumulated deficit to approximately KSh 8.8 billion.
An accumulated deficit represents the total effect of financial shortfalls carried forward over time. It does not necessarily mean the institution borrowed that exact amount from banks or other lenders.
Instead, it indicates that expenses and other financial losses have exceeded income over the relevant periods, creating pressure on the institution’s financial position.
The audit findings also raised concerns about the university’s ability to meet its short-term obligations.
Its current liabilities were reported at approximately KSh 13.79 billion, compared with current assets of about KSh 5.17 billion.
This created negative working capital of approximately KSh 8.62 billion.
Working capital measures the difference between current assets and current liabilities. Current assets generally include cash, receivables and other resources expected to be converted into cash within a relatively short period. Current liabilities include obligations that must be settled within the same period.
When current liabilities significantly exceed current assets, an organisation can struggle to pay suppliers, remit statutory deductions and meet other immediate expenses.
For the University of Nairobi, the difference highlights the challenge of maintaining day-to-day operations while dealing with substantial outstanding obligations.
The Auditor-General’s findings raised material uncertainty about the institution’s ability to continue operating as a going concern without sufficient support from the government and other stakeholders.
This is a serious financial warning, although it should not be interpreted as an announcement that the university is closing or has entered formal liquidation proceedings.
KSh 10.6 Billion in Tax and Pension Obligations
One of the most concerning aspects of the university’s financial position is the reported KSh 10.57 billion in unremitted statutory obligations, including taxes and pension contributions.
The amount was highlighted in reporting on the audit findings presented to lawmakers.
Such obligations are particularly sensitive because they involve money that should be remitted to the relevant authorities or pension arrangements rather than retained indefinitely to support ordinary operations.
Reports put the outstanding tax obligations at approximately KSh 5.01 billion and pension contributions at approximately KSh 5.53 billion.
The reported figures underline the scale of the challenge facing the institution.
Unpaid taxes can expose an organisation to penalties, interest and enforcement action, depending on the applicable laws and circumstances. Delayed pension contributions can also affect the financial arrangements intended to provide retirement benefits to former employees.
For retired university workers, pension contributions are not merely accounting entries. They form part of the financial arrangements that support retirement security.
Delays in remitting such contributions can create uncertainty for employees who depend on their pension arrangements after leaving employment.
The issue also raises questions about the management of payroll deductions and whether sufficient controls are in place to ensure that money collected or withheld for statutory purposes reaches the intended recipients on time.
The university must therefore explain how it intends to settle these obligations, whether through improved cash collection, expenditure reductions, additional funding or other lawful arrangements.
A credible recovery plan will need to identify the outstanding amounts, establish priorities and provide a realistic schedule for meeting the obligations.
How Did the University Accumulate Such a Large Debt?
The financial problems appear to reflect a combination of funding pressures, rising operating costs, accumulated deficits and weaknesses in revenue generation.
University officials have attributed part of the financial strain to changes in government funding arrangements.
According to The Star’s reporting on the parliamentary proceedings, the university’s acting director of finance, Stephen Kimeli, said the introduction of the Differentiated Unit Cost funding model in the 2017/2018 financial year contributed to a funding gap of approximately KSh 1.6 billion.
The model was introduced as part of changes to how public universities were funded. However, the distribution of funding and the amounts institutions received became important issues for universities attempting to meet their operating costs.
When the money available to an institution falls short of the cost of delivering its programmes, management must find ways to bridge the difference.
Those options can include increasing internally generated revenue, reducing expenditure, attracting research grants or seeking additional government support.
If the funding gap persists, the institution may struggle to meet its obligations even when it continues to provide education and other services.
Rising payroll costs have also been cited as a factor contributing to the university’s financial difficulties.
Universities require lecturers, researchers, administrators, technicians, security personnel and other employees to operate effectively. Salaries and employment-related expenses therefore account for a significant share of their budgets.
When staffing costs rise faster than income, the pressure on available funds can become increasingly difficult to manage.
The university must also finance teaching materials, electricity, water, building maintenance, research programmes and other operational requirements.
These expenses continue even when an institution experiences delays in receiving revenue or collecting outstanding fees.
The financial crisis illustrates how a prolonged mismatch between income and expenditure can gradually create a much larger problem.
Why KSh 220 Billion in Assets Has Not Solved the Problem
One of the most striking aspects of the University of Nairobi debt crisis is the contrast between its estimated KSh 20 billion debt burden and the asset portfolio valued at more than KSh 220 billion.
Vice-Chancellor Professor Ayub Gitau cited the institution’s substantial asset base while addressing lawmakers about its financial challenges.
At first glance, the figures may suggest that the university has sufficient wealth to clear its debts.
However, the value of an organisation’s assets is not the same as the amount of cash it has available.
A university can own land, buildings, equipment and other valuable property while lacking the money required to pay its bills immediately.
Land and buildings may take considerable time to sell or lease. Some properties are essential to teaching and research, meaning that disposing of them could undermine the institution’s academic responsibilities.
Other assets may have legal, operational or contractual restrictions that limit how they can be used to generate revenue.
Consequently, the reported KSh 220 billion asset valuation does not automatically mean the university has KSh 220 billion available in its bank accounts.
The central challenge is determining how much of that portfolio can generate sustainable income without compromising the institution’s long-term mandate.
Management has indicated that property leasing and commercialisation are among the measures being considered to improve revenue.
Such initiatives could provide additional income if they are based on reliable valuations, sound contracts and transparent management.
However, the university must demonstrate how much revenue these activities are expected to generate, when the money will become available and how it will be allocated towards outstanding obligations.
Without those details, a large asset portfolio remains a potential resource rather than an immediate solution to a cash-flow crisis.
MPs Question the Performance of Income-Generating Units
Another concern raised during the parliamentary scrutiny involves losses recorded by some of the university’s commercial activities.
Public universities often operate enterprises and specialised units intended to supplement government funding and student-related income.
These activities can include consultancy, professional services, research partnerships, accommodation, property management and other commercial ventures.
When managed effectively, such operations can help institutions diversify their revenue and reduce their dependence on government allocations.
However, commercial activities can also create additional financial pressure when their operating costs exceed the income they generate.
During the parliamentary proceedings, lawmakers questioned the effectiveness of the University of Nairobi’s income-generating strategy because some of its units were reportedly recording losses.
This creates a difficult situation for management.
The university needs additional income to settle debts, but it must also determine whether existing commercial operations are financially sustainable.
One option is to conduct a detailed review of each unit’s performance, including its revenue, operating costs, staffing expenses and outstanding obligations.
Units with a realistic prospect of becoming profitable could receive targeted support and stronger management oversight.
Activities that consistently consume resources without delivering sufficient benefits may require restructuring or other corrective measures.
Any such decisions would need to consider the university’s academic and public-service responsibilities, rather than focusing exclusively on short-term profits.
The broader objective should be to ensure that commercial operations contribute positively to the institution’s financial position.
University Management Outlines Measures to Restore Stability
University officials have indicated that management is pursuing several measures intended to improve its financial position.
According to reporting by The Star, the institution’s strategy includes increasing student enrolment, expanding research activities, improving revenue collection and reviving income-generating units.
Management has also referred to expenditure controls and austerity measures designed to reduce unnecessary costs.
Increasing student enrolment could improve revenue, depending on the funding arrangements applicable to each student and the actual cost of delivering the relevant programme.
However, expansion must be carefully planned because additional students also require teaching staff, learning materials, laboratory capacity and other facilities.
Simply admitting more students would not necessarily solve the crisis if the additional income failed to cover the cost of educating them.
Research funding offers another potential source of revenue. Universities can attract grants and partnerships by developing strong research programmes, collaborating with industry and demonstrating the value of their work.
Nevertheless, research grants often come with specific conditions and cannot automatically be diverted to settle unrelated debts.
Improved revenue collection could also help the university convert outstanding receivables into cash. This would require accurate billing, effective follow-up and clear accountability for money owed to the institution.
Meanwhile, expenditure controls could help management identify unnecessary spending, reduce waste and improve the allocation of limited resources.
The effectiveness of these measures will depend on their implementation and the extent to which they produce measurable financial improvements.
Lawmakers have made it clear that management must provide more than general assurances. The requested recovery plan needs concrete figures, clear timelines and verifiable targets.
What the Debt Crisis Means for Students
For students, the immediate concern is whether the university’s financial difficulties could affect teaching, examinations, research and access to essential services.
A financially stable university requires reliable funding to pay staff, maintain facilities, purchase learning materials and support academic programmes.
When money becomes scarce, institutions can experience difficulties paying suppliers, maintaining infrastructure and financing routine activities.
However, the reported debt figures alone do not establish that examinations will be cancelled, academic programmes suspended or students immediately required to pay higher fees.
Any claims about such consequences would need confirmation from the university or other authoritative sources.
The more immediate issue is whether management can restore financial stability without disrupting academic operations.
Students also have a legitimate interest in transparency because the university’s financial decisions can affect the quality and continuity of the education they receive.
If the institution reduces expenditure, it must distinguish between unnecessary costs and spending that is essential to academic standards.
Cuts that weaken laboratories, libraries, teaching resources or student support could undermine the university’s core responsibilities.
Conversely, improved financial management could help the institution allocate resources more efficiently and reduce the risk of future disruptions.
The recovery process must therefore balance financial discipline with the need to protect teaching, research and the student experience.
What the Debt Crisis Means for Staff and Pensioners
University employees are another group with a direct interest in the institution’s financial recovery.
Academic and non-academic staff depend on the university to meet its employment obligations, while former employees may rely on pension arrangements for retirement income.
The reported outstanding pension contributions have made the crisis particularly sensitive for retirees and current workers approaching retirement.
A credible recovery strategy should explain how pension obligations will be verified, prioritised and settled in accordance with the applicable requirements.
Staff members also need confidence that the university can manage its payroll and other employment-related expenses without repeatedly accumulating new arrears.
Financial recovery should not depend solely on postponing payments to employees or suppliers, because such an approach could simply shift the burden from one part of the institution to another.
Instead, management needs a sustainable plan that addresses both existing liabilities and the underlying reasons the debts accumulated.
This includes monitoring payroll costs, improving revenue collection, reviewing commercial operations and ensuring that available funding is directed towards essential obligations.
Clear communication with employees and pensioners would also help them understand the recovery process and distinguish between confirmed measures and proposals that are still under consideration.
A Wider Financial Challenge for Kenya’s Public Universities
The University of Nairobi’s difficulties come amid broader concerns about the financial sustainability of public higher education institutions in Kenya.
Universities must finance academic programmes, maintain infrastructure, support research and meet employment obligations while operating within the limits of their available resources.
A 2023 report by the Presidential Working Party on Education Reform identified underfunding, changes in student enrolment, rising operating costs and other pressures as contributors to financial challenges in public universities.
The report documented substantial pending bills across the public university sector, highlighting that the difficulties were not confined to one institution.
This wider context is important because universities play a major role in producing graduates, supporting research and supplying skilled workers to different sectors of the economy.
Persistent financial instability can limit their ability to invest in laboratories, modernise equipment, recruit and retain skilled personnel, and expand academic programmes.
It can also increase pressure on the government to provide additional support at a time when public resources must meet competing demands.
However, the challenges facing the sector do not eliminate the need for institution-specific accountability.
Each university must maintain reliable financial records, monitor expenditure, comply with statutory obligations and demonstrate how public resources are being used.
Government funding policy and university management practices both matter when assessing the causes of financial distress.
A sustainable solution will require funding arrangements that reflect the cost of delivering quality education, alongside stronger financial controls and more effective revenue generation.
What Happens Next?
The next major development is expected to centre on the University of Nairobi’s response to the parliamentary committee’s demands.
The December 1, 2026, deadline requires management to explain how it plans to address its financial obligations and restore stability.
A meaningful recovery plan should provide a clear breakdown of the reported debt, distinguish statutory arrears from other liabilities and explain how the university intends to meet its obligations.
It should also contain realistic financial projections, including expected revenue, operating expenditure, cash-flow requirements and the anticipated contribution of proposed commercial activities.
Management will need to demonstrate how its plans can reduce existing debts without creating additional arrears.
The committee’s scrutiny could also help establish whether the proposed measures are being implemented effectively and whether further intervention is necessary.
For the university, the challenge is to turn its substantial asset base and academic reputation into a financially sustainable operating model.
For the government, the crisis raises questions about the adequacy and predictability of funding for public higher education.
For students, staff and pensioners, the priority is ensuring that the university can meet its obligations while continuing to deliver quality education.
A Financial Recovery Plan Will Be Crucial
The University of Nairobi’s reported KSh 20 billion debt burden has exposed serious questions about the institution’s financial sustainability, despite its extensive assets and long-standing role in Kenyan higher education.
Audit findings pointing to accumulated deficits, negative working capital and substantial outstanding tax and pension obligations explain why lawmakers are demanding a detailed recovery strategy.
The university’s management has identified several possible measures, including improved revenue collection, property leasing, increased student enrolment, research funding and tighter expenditure controls.
Whether these measures can deliver lasting improvements remains to be demonstrated through transparent financial projections and measurable results.
The December 1 deadline gives the institution an important opportunity to show how it intends to address the crisis.
Ultimately, the issue is not simply whether the University of Nairobi owns valuable property. It is whether the institution can generate sufficient sustainable income, meet its obligations and protect the academic mission on which thousands of students and the wider country depend.
SUGGESTED READS
- Where Is Paul Biya? Inside the Cameroonian President’s Long Stays in Switzerland
- How Inflation Destroyed Zimbabwe’s Currency: The Shocking Story of Money That Became Almost Worthless
- Why Do People Go Back to Someone Who Hurts Them? The Psychology Behind Toxic Relationships
- Can Your Brain Create a Memory That Never Happened? The Truth About False Memories
- Elifasi Msomi: The Axe Killer Who Terrorised Rural Natal
- Why Do Strangers Sometimes Look Familiar? The Fascinating Science Behind That Feeling
- Africa’s Social Media Obsession: The Countries Spending More of Their Lives Online
Support Our Website!
We appreciate your visit and hope you find our content valuable. If you’d like to support us further, please consider contributing through the TILL NUMBER: 9549825. Your support helps us keep delivering great content!
If you’d like to support Nabado from outside Kenya, we invite you to send your contributions through trusted third-party services such as Remitly, western union, SendWave, or WorldRemit. These platforms are reliable and convenient for international money transfers.
Please use the following details when sending your support:
Phone Number: +254701838999
Recipient Name: Peterson Getuma Okemwa
We sincerely appreciate your generosity and support. Thank you for being part of this journey!